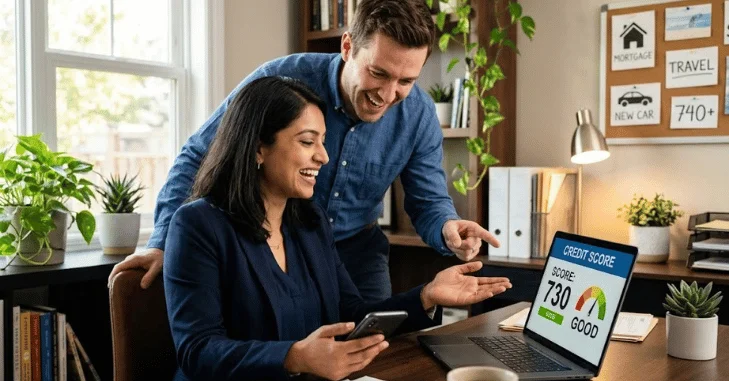
A 730 credit score is considered good under the widely used FICO scoring model. It can help you qualify for many mainstream loans and credit cards. Still, moving higher may improve the rates or terms some lenders offer.
FICO places scores from 670 through 739 in its Good range. Scores from 740 through 799 fall into its Very Good category. That makes 740 a useful milestone if you are already close.
| Key point | What 730 generally means |
|---|---|
| FICO category | Good |
| FICO Good range | 670–739 |
| Distance from Very Good | 10 points |
| Credit cards | Many mainstream options may be available |
| Mortgages | A strong starting point, subject to full underwriting |
| Auto loans | Competitive options may be available |
| Personal loans | Approval may be possible with suitable income and debt levels |
| Main improvement priorities | On-time payments, lower balances, fewer unnecessary applications |
Direct answer: A 730 score is good for a U.S. borrower. It may qualify you for many credit cards, mortgages, auto loans, and personal loans. Approval is never guaranteed because lenders also review income, debts, payment history, loan size, and other application details.
Is a 730 Credit Score Good?
Yes, a 730 credit score sits near the upper end of FICO’s Good category. You are only ten points below the start of the Very Good range. That can make modest improvements worth considering before a large loan.
A higher number does not automatically guarantee approval or the lowest advertised rate. Lenders can use different scoring versions and separate underwriting standards. Your income, existing debt, recent applications, and payment history can also influence an offer.
The number may also look different under another scoring system. VantageScore uses its own ranges and calculations. A lender might also use a specialized score for mortgages, vehicles, or another credit product.
How 730 Compares With FICO Ranges
| FICO range | Rating |
|---|---|
| Below 580 | Poor |
| 580–669 | Fair |
| 670–739 | Good |
| 740–799 | Very Good |
| 800 and above | Exceptional |
Higher scores generally indicate lower lending risk under the FICO model. That can help borrowers qualify for more competitive offers. Individual lenders still decide which thresholds matter for each product.
What Can You Qualify for With a Good Credit Score?
A strong score can open several borrowing options, but it is only one part of approval. Lenders often examine income, monthly obligations, account history, and recent applications. They may also apply product-specific eligibility rules.
Your actual offer matters more than a general score range. Two lenders can view the same applicant differently. Comparing several offers can reveal meaningful differences in rates, fees, and repayment terms.
Credit Cards
Someone around this range may qualify for many cash-back, travel, rewards, and introductory-rate cards. Premium cards can have stricter approval standards or additional income requirements. Issuers do not publish guaranteed approval rules for every applicant.
Compare the annual fee, rewards structure, and ongoing interest rate before applying. Understanding how purchase APR works can help you estimate the cost of carrying a card balance. Interest costs may outweigh rewards if you regularly carry a balance month to month.
Paying the full statement balance can often prevent purchase interest when a grace period applies. Grace-period rules vary by issuer and account. Your cardholder agreement controls the exact terms.
Mortgages
A score near 730 can put a homebuyer in a competitive position for many mortgage programs. Mortgage approval still depends on far more than one three-digit number. Lenders can review income, assets, employment, debts, down payment, and the property itself.
Conventional lenders set their own underwriting and pricing rules. Government-backed programs also have separate eligibility standards. A small score increase could affect pricing with some lenders, but there is no universal 740 rule.
Shop among several lenders rather than assuming one offer represents the market. Compare the rate, annual percentage rate, points, lender fees, and cash needed at closing. Those details can substantially change the real cost of borrowing.
Auto Loans
A good score can also help you access competitive vehicle financing. Lenders may use specialized auto-scoring models instead of the score shown in a consumer app. The vehicle, term, down payment, and lender can also affect your offer.
Consider checking prequalification options before visiting a dealership. Readisave’s guide to Capital One auto financing explains one example of how auto prequalification can work. Comparing that information with dealer financing can give you another reference point.
Focus on total financing cost, not just the monthly payment. A longer term can reduce monthly payments while increasing total interest. A larger down payment can also reduce the amount you need to finance.
Personal Loans
Personal loan lenders commonly examine both credit history and ability to repay. A good score may improve access to unsecured borrowing. Your income, existing debt, and requested amount can still change the outcome.
Rates can vary significantly among banks, credit unions, and online lenders. Readisave’s overview of Mountain America personal loans provides one example of a credit-union lending option. Compare eligibility, rates, fees, and repayment terms before choosing any lender.
Borrow only when the loan serves a clear financial purpose. Debt consolidation may help when it reduces costs and supports a realistic repayment plan. Taking a loan solely to change your score can create unnecessary interest expense.
Why Reaching 740 Can Matter
FICO places 740 at the beginning of its Very Good category. That does not mean every lender changes pricing at exactly 740. It does give borrowers a useful benchmark when they are already close.
Reaching a higher tier could improve offers from some lenders. The potential value may be greater before a large borrowing event, such as a mortgage. Even a small pricing difference can matter when a large balance remains outstanding for years.
Don’t delay a necessary financial decision just to chase ten points. Compare real offers at your current score first. A competitive rate may already be available based on your complete financial profile.
How to Move From 730 Toward 740 and Above
You do not need unusual tactics to improve a 730 credit score. The strongest approach is usually consistent management of the information already reported. Focus first on factors you can change without taking on unnecessary debt.
- Pay every bill on time. Payment history is an important scoring factor. Set automatic payments or reminders before each due date.
- Reduce revolving balances. Lower card balances can reduce utilization. Avoid getting unnecessarily close to your credit limits.
- Check all three reports. Look for incorrect balances, unfamiliar accounts, or wrongly reported late payments.
- Dispute genuine errors. Contact the reporting company and information provider when information is inaccurate.
- Limit unnecessary applications. Applying for several accounts can create multiple hard inquiries.
- Keep useful older accounts carefully. Closing a card may reduce your available revolving credit.
- Avoid borrowing solely for credit mix. You don’t need to pay interest just to add another account type.
Lower revolving balances can help when high utilization is holding your profile back. Payment consistency also matters because missed payments can damage an otherwise strong history. Neither step requires opening a new account.
Reviewing your credit reports can also uncover reporting mistakes before an important application. The Consumer Financial Protection Bureau says consumers can review reports online for free once a week from each of the three nationwide credit reporting companies. The CFPB also states that requesting your own credit report does not hurt your score.
What Can Lower a Good Score?
Late payments can damage an otherwise strong credit history. High revolving balances can also make your profile appear riskier. Several new applications within a short period may create additional pressure.
Closing an older card without considering utilization can create another issue. Your total available revolving limit may fall while existing balances remain unchanged. The resulting utilization percentage can rise even without new spending.
Do not assume every score movement means something went wrong. Scores can change as reported balances update throughout the month. Different scoring models may also produce different numbers from the same credit file. Also worth reading: Exempt From Withholding.
Should You Apply for Credit Now or Wait?
Start with the purpose of the application, not the number alone. If you need financing now, compare available offers before deciding you need to wait. A lender may already offer terms that meet your needs.
Waiting can make sense before a major loan when reducing balances is realistic. It may also help when an inaccurate report item needs correction. Whether waiting helps depends on whether those changes strengthen your overall application.
Avoid opening several accounts while preparing for a major borrowing decision. New accounts can add hard inquiries and reduce your average account age. A stable credit profile can make lender comparisons easier.
Ways to Protect Your Score Before a Major Loan
Keep credit card spending predictable during the months before a mortgage or large auto loan. Large reported balances can change utilization even when you plan to pay them later. Paying balances before statements close may reduce reported amounts in some cases.
Continue making every payment on time. A late payment creates a problem that a small score increase may not offset. Automatic minimum payments can provide a backup if you normally pay manually.
Avoid changing several parts of your credit profile at once. Opening cards, closing older accounts, and financing purchases can make your file less stable. Make changes only when they serve a clear financial purpose.
Frequently Asked Questions
Is a 730 Credit Score Considered Excellent?
No, not under FICO’s standard categories. FICO classifies 670 through 739 as Good and 740 through 799 as Very Good. Scores of 800 or higher fall into its Exceptional category.
Can I Buy a House With a 730 Score?
A borrower around this level may meet the score expectations of many mortgage lenders. Approval also depends on income, debt, down payment, assets, and underwriting rules. Compare several loan estimates before choosing a mortgage.
Can I Get a Good Credit Card at This Level?
Many cards designed for consumers with good credit may be within reach. Approval still depends on the issuer’s complete review of your application. Compare fees, rewards, introductory offers, and ongoing rates before applying.
How Long Does It Take to Move From 730 to 740?
There is no guaranteed timeline because credit files differ. Lower reported balances or corrected errors can sometimes produce changes faster than long-term factors. Payment history and account age generally require consistent behavior over time.
Will Checking My Own Score Lower It?
Checking your own credit information does not normally create a hard inquiry. Consumer-requested credit-report checks are treated differently from lender inquiries tied to applications. That means you don’t need to avoid routine monitoring because of score concerns.
Is 740 Always Better Than 730 for Loan Rates?
A higher score can help, but lenders do not all use identical pricing tiers. One lender may price both applicants similarly while another uses different thresholds. Compare actual offers rather than assuming ten points guarantees a specific discount.
Make Your Good Credit Work for You
A score of 730 already places you in a healthy FICO range. Your next move should depend on your financial goal, not the score alone. Protect your payment history and keep revolving balances manageable.
If you expect to borrow soon, review your reports before applying. Correct genuine errors and compare several lenders or card issuers. Small differences in rates and fees can matter more than chasing a perfect number.
Use your score as one part of a larger borrowing decision. Compare APR, fees, repayment length, monthly cost, and total interest together. Those figures show whether an offer truly fits your budget.